Free tool · Working capital calculator
Working capital: the formula, a calculator, and the cash your business has tied up.
Working capital is current assets minus current liabilities: your cash, the money customers owe you and your stock, less everything you have to pay in the next 12 months. Positive means you can pay what is coming. The calculator goes one step further and shows how much cash is stuck in the cycle, and how much you could get back.
Strictly private. The figures you type stay on your device. They are never sent to us or kept on our servers. The only details we hold are your name and email.
How it works
What is working capital?
Working capital is the money tied up in running the business day to day. It is what you have that will turn into cash within a year, less what you will have to pay out within a year. Your accountant calls the first half current assets and the second half current liabilities.
The bank balance is one line of it. The money customers owe you and the stock on the shelves will turn into cash over the coming weeks, while the VAT bill and the supplier invoices will take cash out over the same weeks. Working capital adds all of that up into one figure.
How do you calculate working capital?
The working capital formula:
Working capital = current assets − current liabilitiesCurrent assets = cash + trade debtors + stock and work in progressCurrent liabilities = trade creditors + VAT, PAYE and tax due + overdraft + other bills due within 12 monthsThe ratios and days that tell you whether that number is healthy:
Current ratio (working capital ratio) = current assets ÷ current liabilitiesQuick ratio = (current assets − stock) ÷ current liabilitiesDebtor days = trade debtors ÷ turnover × 365Stock days = stock ÷ cost of sales × 365Creditor days = trade creditors ÷ cost of sales × 365Cash conversion cycle = debtor days + stock days − creditor daysAnd the two that matter most to an owner:
Cash tied up in the cycle = trade debtors + stock − trade creditorsCash freed by cutting debtor days = turnover ÷ 365 × days cutWorking capital example
The calculator opens with a £2m turnover business: £60,000 in the bank, £330,000 owed by customers, £150,000 of stock, £180,000 owed to suppliers and £90,000 of VAT, PAYE and other bills due. Current assets are £540,000 and current liabilities £270,000, so working capital is £270,000 and the current ratio is 2.0. Take the stock out and the quick ratio is 1.44.
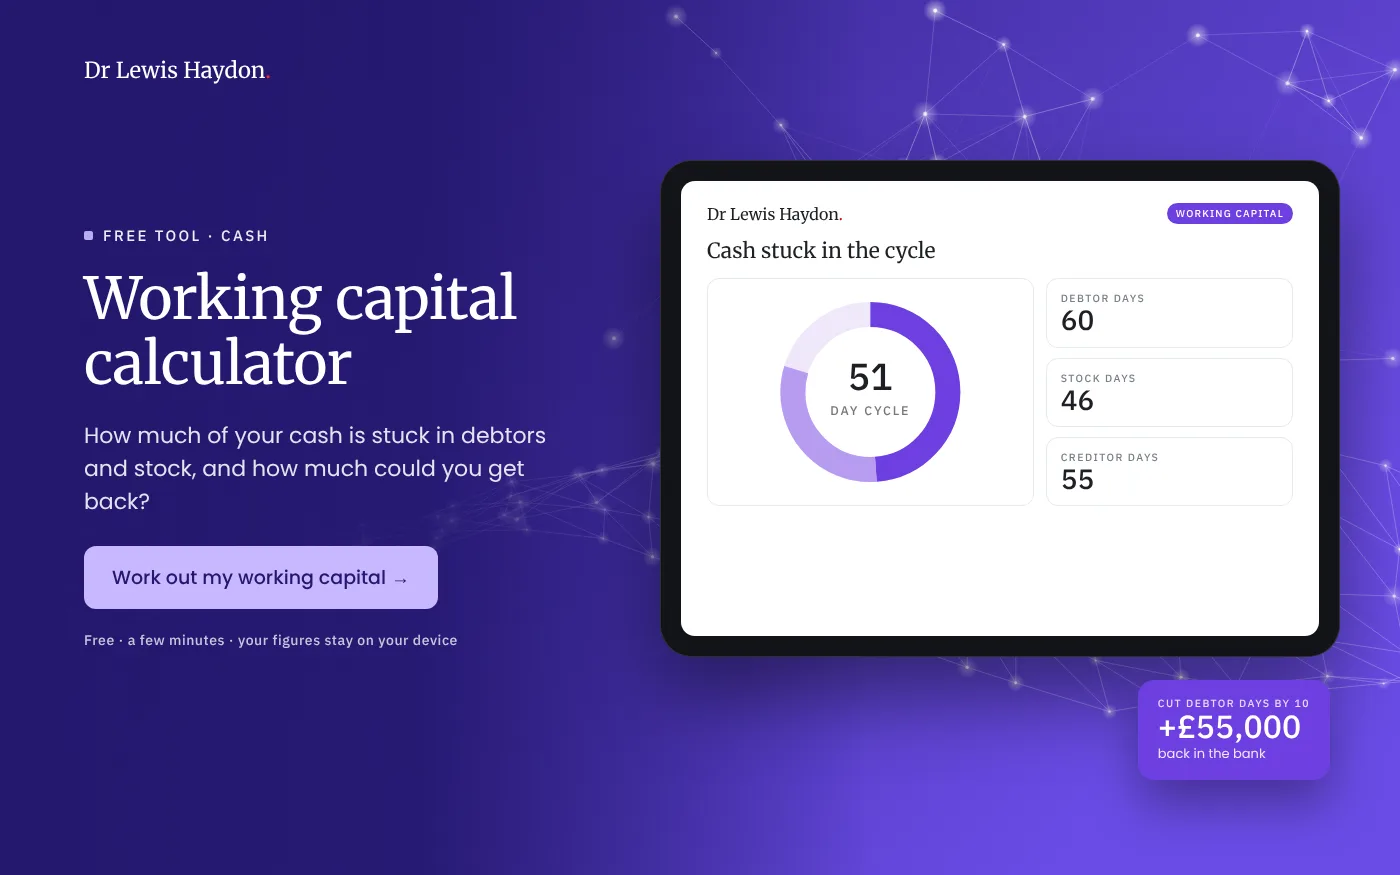
Customers take 60 days to pay against 30-day terms. Stock sits for 46 days. The business takes 55 days to pay its suppliers. The cash conversion cycle is 51 days, and £300,000 is tied up in debtors and stock after what suppliers fund. Cut debtor days by 10 and £54,795 lands in the bank once, with no extra sales. Get customers paying on 30-day terms and it is £165,616.
What is a good working capital ratio?
| Current ratio | What it usually means |
|---|---|
| Below 1.0 | You owe more in the next 12 months than you have coming in. One slow payer or a tax bill in the wrong week and you are short. |
| 1.0 to 1.2 | Tight. You can pay what is due, but only if customers pay on time. The 13-week forecast needs to be a weekly habit. |
| 1.2 to 2.0 | Comfortable for most trading businesses. |
| Above 2.0 | Safe, but check why. Cash sitting idle, debtors who pay slowly or stock that doesn't move all push the ratio up and earn you nothing. |
Look at the quick ratio alongside it. Stock is the slowest current asset to turn into cash, so a business with a current ratio of 1.5 and a quick ratio of 0.6 is relying on selling stock to pay its bills. Sectors differ: a services business with no stock will have the two ratios almost the same, and a retailer will run lower than a manufacturer. Compare with businesses in your sector.
Why do profitable businesses run out of cash?
Because profit is booked when you invoice and cash arrives when the customer pays. In between, you have paid the wages, the suppliers and the VAT on a sale you haven't been paid for. That gap is the working capital cycle, and it grows with you: every extra £100,000 of turnover on a 51-day cycle needs roughly another £14,000 of cash before it brings any in.
The cycle isn't only a cash question. A study of 8,872 Spanish small and medium-sized businesses found that shorter debtor days, lower stock and a shorter cash conversion cycle all went with higher profitability (García-Teruel and Martínez-Solano, 2007). The businesses that got paid faster and held less stock also made more money.
Late payment is usually the biggest part of it. More on the causes and the seven-day fix in cash flow problems, and see the next 13 weeks with the 13-week cash flow forecast.
How do you free up working capital?
Get paid sooner, hold less stock and keep fair terms with suppliers. Start with the terms you give customers, because that's the part of the cycle you set.
When I coach clients on terms, I ask what the ultimate terms would be. "Lewis, we'd love to get down to 30 days. We'd love to get down to 14." What would be the ultimate? Paying straight away. So why aren't they? Because they've got this excuse that they have to do 30 days. Okay, so what would need to be true to meet in between? Would you walk into Apple, buy a Mac and tell them you'll pay on 180-day terms? No. You pay for it, or you finance it, and either way Apple gets paid straight away. Make the product and the service good enough and you can have that conversation too.
Then the rest:
- Invoice the day the work is done. Every day between finishing a job and sending the invoice is a day added to debtor days.
- Chase on the day it is due, not a month later. Give one person the job and a weekly number to report.
- Ask for deposits and stage payments on anything that takes weeks to deliver.
- Run stock down to what actually sells. You've already paid for stock that sits on the shelf for months.
- Agree fair terms with suppliers, then keep to them. Paying suppliers late to fix your own cash just moves the problem on to another owner, and you'll need that relationship later.
What happens to working capital when you sell a business?
Sellers often miss this. A buyer agrees a price for the business on a cash-free, debt-free basis, and expects it to come with a normal level of working capital so it can keep trading on day one. That normal level is the working capital peg, usually the average of the last 12 months.
Price adjustment = working capital on completion − the pegIf there is less working capital than the peg on completion day, the price comes down pound for pound. If there is more, it goes up. So there's no point collecting every debt and running stock down in the months before a sale, because the buyer takes it back in the working capital adjustment. A shorter cycle you've run for a year or more is different. It lowers the peg, and the cash it freed is already yours before the deal.
Work out what the business is worth with the business valuation calculator, and see the whole process in how to sell a business.
Questions people ask
Do you keep my figures?
No. The sums run on your own device: the figures you type are never sent to us or kept on our servers, and they stay strictly private. To see your result you enter your name and email, and those are the only details we hold.
What is working capital in simple words?
It is the money the business has to keep running day to day: the cash in the bank, the money customers owe you and the stock you hold, minus the bills you have to pay in the next 12 months. Positive working capital means you can cover what is coming; negative means you are relying on money you have not been paid yet.
How do you calculate working capital?
Add up your current assets (cash, trade debtors, stock and work in progress) and take away your current liabilities (trade creditors, VAT and PAYE due, corporation tax, the overdraft and anything else due within 12 months). A business with £540,000 of current assets and £270,000 of current liabilities has £270,000 of working capital.
What is a good working capital ratio?
The working capital ratio, also called the current ratio, is current assets divided by current liabilities. Below 1 means you owe more in the next year than you have coming in. Between 1.2 and 2 is comfortable for most trading businesses. Well above 2 can mean cash sitting idle, or debtors and stock that are too high. What is normal varies by sector, so compare yourself with businesses like yours.
Is negative working capital always bad?
Not always. Supermarkets and some subscription businesses are paid by customers before they pay their suppliers, so they run negative working capital on purpose. For most owner-managed businesses that invoice on credit, negative working capital means the next VAT bill or a slow-paying customer could leave you short.
What is the difference between working capital and net working capital?
Usually nothing: both mean current assets minus current liabilities. In a business sale, though, net working capital often means trade working capital only (trade debtors plus stock minus trade creditors), with cash and borrowing left out, because the price is agreed on a cash-free, debt-free basis.
How do you calculate debtor days?
Trade debtors divided by annual turnover, times 365. £330,000 owed to you on £2,000,000 of turnover is 60 days. Your debtors usually include VAT and your turnover does not, so a VAT-registered business will read a few days high; it is the trend that matters.
What is the cash conversion cycle?
The number of days between paying for what you sell and being paid for it: debtor days plus stock days minus creditor days. A cycle of 51 days means every pound you spend delivering work comes back as cash 51 days later, and growth has to be funded for those 51 days.
What is a working capital peg?
The normal level of working capital a buyer expects to be left in the business on completion, usually the average of the last 12 months. If there is less than the peg on the day, the price comes down pound for pound; if there is more, it goes up. It stops a seller collecting every debt and running stock down before the sale.
References
- García-Teruel, P.J. and Martínez-Solano, P. (2007) 'Effects of working capital management on SME profitability', International Journal of Managerial Finance, 3(2), pp. 164–177. Available at: https://doi.org/10.1108/17439130710738718.
Built by Dr Lewis Haydon, business coach and mentor, Birmingham, UK. Related: the profit margin calculator and the 13-week cash flow forecast.
Next step
Profitable, but the cash never seems to arrive?
Bring your numbers to a 30-minute virtual coffee and leave with a straight answer on where your cash is stuck and what to fix first.